Selasa, 19 Juli 2011

Greece May Be Allowed "Temporary Default," Assault on CPI Calculation Continues, and 8 Ways to Bring Down the Banking System

Besides the continuous sideshow that is the Rupert Murdoch scandal (complete with foam launching and increased bets of U.K. Prime Minister David Cameron resigning from 100/1 odds to 8/1!)  Europe's big news today was the partial-admittance that, *gasp*, Greece may default!  Don't get too excited though, it is only temporary:
European Central Bank council member Ewald Nowotny suggested the bank may compromise and allow a temporary Greek default as officials scramble to fix a sovereign debt crisis that’s spreading to Italy and Spain before a leaders’ summit in two days.
Hmmm...I bet this soon-to-end moment of clarity had something to do with this:
Greece
The fact that the yield of a 2 year Greece bond nearly reaching 40% may require telling a few creditors to feck off wasn't the only moment of clarity today, check out this nugget from Portugal Prime Minister Pedro Passos Coelho today:
"Portugal's new leader Pedro Passos Coelho has told the nation to brace for further austerity measures after his government discovered a "colossal" €2bn (£1.7bn) hole in the public accounts left by the outgoing Socialists."
European socialists lying about squandered tax dollars?  Well I never!  While many Euro citizen's blind faith in their elected leaders to run their respective countries into bankruptcy all while delivering thousands upon thousands of transfer payments for non-work should serve as a lesson for the rest of the world, you wouldn't get that impression judging from the likes of government/Keynesian worshipers like Obama's former director of the White House National Economic Council (so you know he is good!) Larry Summers.  In a recent interview with Charlie Rose:
Never forget, never forget, and I think it’s very important for Democrats especially to remember this, that if Hitler had not come along, Franklin Roosevelt would have left office in 1941 with an unemployment rate in excess of 15 percent and an economic recovery strategy that had basically failed.
Well here I thought I had heard everything, but then here comes a former U.S. Treasury Secretary and President of Harvard University actually praising not one, but two fascists!  So let me get this straight: for the almost ten years prior to WWII Roosevelt was in office saving capitalism (as if regulating the hell out of it constitutes as saving it), spending exorbitant amounts of money, and micromanaging the economy by arresting such criminals who sold their goods below a government approved "fair price," the economic recovery everyone thought would come didn't.  Before our entrance into World War II, as Summers graciously points out, unemployment was still persistently high and a genuine recovery was nowhere on the horizon.  But according to Summers, a tarnished record for Franklin Roosevelt and government intervention into the economy would be such a horrible thing to have so thank God a mass murderer came along that forced the U.S. government to devote millions of dollars of resources towards fighting another war.

What sort of sheltered, demented world do guys like Summers come from?
 But wait, I am not done with my idiot list for the day yet.  Check out this brilliant solution on how to end the U.S. government's current debt problem:
Philippa Malmgren, a former advisor to the Bush administration, has told CNBC the US debt must be paid off.

Malmgren, who was a member of the Plunge Protection Team when she worked in Washington D.C.  for the Bush Administration, is no Ron Paul. She said the debt crisis could be solved easily by having everybody work an extra 10 years and that it will happen.
That's right America, because Congress has spent your tax dollars appeasing labor unions, Wall Street, military contractors, and senior citizens, all you gotta do is work 10 more years to pay it off!  Who's in??

After all that lunacy, perhaps it is time for some actual intelligence.  I heard Glenn Beck (don't ask) talking about this on the radio this morning.  Here is mulit-million dollar business man Steve Wynn on the Obama administration's brilliant economic policy thus far:
I believe in Las Vegas, I think its best days are ahead of it, but I'm afraid to do anything in the current political environment in the United States.  You watch television and see what's going on on this this debt ceiling issue.  And what I consider to be a total lack of leadership from the President, and nothing will get fixed until the President himself steps up and wrangles both parties in Congress.  But everybody is so political, so focused on holding their job for the next year, that the discussion in Washington is nauseating.

And I'm saying it bluntly that this administration is the greatest wet blanket to business and progress and job creation in my lifetime.  And I can prove it and I could spend the  next three hours giving you examples of all of us in this marketplace that are frightened to death about all the new regulations, our health care costs escalate.  Regulations coming from left and right.  A President that seems, you know -- that keeps using that word redistribution.
Chalk up another one person from the business community criticizing the current administration.

Okay, so on this blog I have been keep tracking of a proposal in Congress to reign in the debt by essentially messing with the calculation of the Consumer Price Index to underscore inflation in order to pay out smaller and smaller COLA payments for Social Security recipients.  It's basically the last refuge of inflationists trying to cover their tracks. Well, the proposal in Congress is continuing to gain traction:
According to a copy of a summary of the Gang of Six plan, obtained by POLITICO, the group would impose a two-step legislative process that would make $500 billion worth of cuts immediately followed by a second bill to create a “fast-track process” that would propose a comprehensive bill aimed at dramatically restructuring tax and spending programs. The plan calls for changes to Social Security to move on a separate track, and establishes an elaborate procedure for considering the measures on the floor.
The $500 billion in cuts would come from a range of sources, including shifting to a new consumer price index to make cost-of-living adjustments to Social Security. The plan would impose statutory spending caps through 2015, freeze congressional pay and sell unused federal property.
Remember baby boomers, just because the price of meat goes up doesn't mean that catfood isn't a legitimate alternative.  And just because Wall Street gets all those newly printed greenbacks first doesn't mean you are losing out, some people just get luckier than others.
But seriously though, if understating inflation in order to increase the monetary base even more isn't another gift to the bankers than I don't know what is.

Thankfully, Charles Hugh Smith over at Of Two Minds has a unique solution on how to fix the U.S. economy in 8 easy steps:
1. Force all banks to mark all their assets to market at the end of each trading day, including all derivatives of all types, including over-the-counter instruments.

2. Allow citizens to discharge all mortgage and student loan debt in bankruptcy court, just like any other debt.
3. Banks must mark all their real estate to market weekly as defined by "last sales of nearby properties" adjusted for square footage and other quantifiable measures (i.e. like Zillow.com).
4. Require mortgage servicers and all owners of mortgage-backed securities to mark every asset within each pool to market weekly.
5. Any mortgage, loan or note which was fraudulently originated, packaged and sold, including the misrepresentation of risk, the manipulation of risk ratings, fraudulent documentation by any party, etc., will be discharged as uncollectable and the full value wiped off the books and title records without recourse by any of the parties.
If a bank fraudulently originated a mortgage and the buyer misrepresented material facts on the mortgage documents, then both parties lose all claim to the note and the underlying asset, the house, which reverts to the FDIC for liquidation, with the proceeds going towards creditors' claims against the bank.
6. Any bank which misrepresents marked-to-market asset values will be fined $10 million per incident.
7. Any bank which is insolvent at the end of a trading day will be closed and taken over by the FDIC the following day, and liquidated in an orderly manner via open-market auctions of all assets, including REO (real estate owned).
8. All derivative positions held by the insolvent bank will be unwound immediately, and counterparties who fail to make good on their claims will also be closed, given to the FDIC and liquidated.

Of course such action would practically destroy the banking system, but that wouldn't necessarily be a bad thing consider the path they are on already.  Don't look for Obama embracing the plan anytime soon though despite his "eat the rich" rhetoric:
In late June Barack Obama huddled over a meal in New York with business and finance industry heavyweights, who paid $35,000 a head for the privilege of dining with the president at the upmarket French eatery, Daniel.
Mr Obama reported in filings with the Federal Election Commission on Friday that he had raised $86m in the three months to the end of June, $46m for his own campaign and just under $40m for the Democratic National Committee.
I will end with another great interview with Ron Paul on Yahoo! Finance:
Score another one for the Austrian Business Cycle Theory on slightly mainstream media!

Senin, 18 Juli 2011

European Bond Bloodbath, Goldman Sachs Keeps the Revolving Door Spinning 83 Times, and Iran-Israel War Coming In September?

Due to last week's European bank stress tests, bond yields for all the PIIGS keep sizzling:
Greece
Ireland
Italy
Spain
Apparently Italy's 10-year hit 6%.  This is going to cause a great deal of conflict come Thursday when European leaders will meet for another summit that will surely accomplish nothing.  How these morons keep up the dog and pony show is beyond me.  Still, as Europe continues to sink, gold has hit a brand new high of $1,600:
I guess it's this type of uncertainty that drives the price of gold Bernanke was referring to.  I have always wanted to know if Bernanke holds any gold stocks, he clearly has the power to make a fortune off them.  The New Yorker has an interesting interview with the owner of the world's largest hedge fun, Ray Dalio.  Dalio just reiterates with anyone with a brain already knows:
Dalio believes that some heavily indebted countries, including the United States, will eventually opt for printing money as a way to deal with their debts, which will lead to a collapse in their currency and in their bond markets. “There hasn’t been a case in history where they haven’t eventually printed money and devalued their currency,” he said. Other developed countries, particularly those tied to the euro and thus to the European Central Bank, don’t have the option of printing money and are destined to undergo “classic depressions,” Dalio said. The recent deal to avoid an immediate debt default by Greece didn’t alter his pessimistic view. “People concentrate on the particular thing of the moment, and they forget the larger underlying forces,” he said. “That’s what got us into the debt crisis. It’s just today, today.”

Dalio’s assessment sounded alarmingly plausible. But when one plays the global financial markets a thorough economic analysis is only the first stage of the game. At least as important is getting the timing right. I asked Dalio when all this would start to come together. “I think late 2012 or early 2013 is going to be another very difficult period,” he said.
And reports like these only add fuel to the banker-government incestual fire:
The Sunlight Foundation Reporting Group has made those logs--published by five separate federal agencies--available in one location in and easy-to-search format, updated to include the most current information on contacts between officials and private interests seeking to influence federal regulators. 
Agency officials reported 83 meetings with Goldman Sachs executives across numerous agencies. In June alone, government agencies reported 21 meetings with the firm--or almost one meeting for every workday that month. And on one day, June 14, Goldman Sachs representatives were present at four separate meetings with officials from the Commodity Futures Trading Commission (CFTC), to discuss various aspects of swap trading rules and reporting.
Overall, government officials have reported more than 2,100 meetings with outside parties since the passage of the Dodd-Frank Wall Street Reform and Consumer Protection Act last year. Other institutions showing up at the top of the most frequent visits list include JP Morgan Chase, with 73 meetings, Morgan Stanley, with 58 meetings, and Bank of America, with 55 meetings.
Yet those on the left still think all those angels they voted into Congress don't fall under the spell of easy money.  Like always, Ron Paul nails it:
We are headed for rough economic times either way, but the longer we put it off, the greater the pain will be when the system implodes.  We need to stop adding more programs and entitlements to the problem.  We need to stop expensive bombing campaigns against people on the other side of the globe and bring our troops home.  We need to stop allowing secretive banking cartels to endlessly enslave us through monetary policy trickery.  And we need to drastically rethink government's role in our lives so we can get it out of the way and get back to work.
Yesterday Zerohedge broke a very interesting article that seems to be causing a stir across the blogosphere.  Even Nourial Roubini tweeted about it.  The subject?  The possible brewing of WWIII
As the most recently updated naval map from Stratfor demonstrates, the CVN 77 G.H.W. Bush has just entered the Persian Gulf, the first time a US aircraft carrier has passed through the Straits of Hormuz in months. What is also notable is that the LHD 5 Bataan amphibious warfare ship has just weighed anchor right next to Libya: this is odd since the coast of Tripoli had been left unattended for many weeks by US attack ships. And topping it all off is that a third aircraft carrier, the CVN 73, is sailing west from the South China seas, potentially with a target next to CVN 76 Ronald Reagan which is the second carrier in the Straits of Hormuz area. Three carriers in proximity to Iran would be extremely troubling.
Yeah yeah, U.S. warships in the Middle East, what's new?  Al Jazeera has it:
A longtime CIA officer who spent 21 years in the Middle East is predicting that Israel will bomb Iran in the fall, dragging the United States into another major war and endangering US military and civilian personnel (and other interests) throughout the Middle East and beyond.
Earlier this week, Robert Baer appeared on the provocative KPFK Los Angeles show Background Briefing, hosted by Ian Masters. It was there that he predicted that Israeli Prime Minister Binyamin Netanyahu is likely to ignite a war with Iran in the very near future.
He obviously won't name many of his sources in Israel, the United States, and elsewhere, but the few he has named are all Israeli security figures who have publically warned that Netanyahu and Defense Minister Ehud Barak are hell-bent on war.
There is almost "near certainty" that Netanyahu is "planning an attack [on Iran] ... and it will probably be in September before the vote on a Palestinian state. And he's also hoping to draw the United States into the conflict", Baer explained.
People make predictions like this all the time, but the fact that Nouriel Roubini tweeted about it gives it more weight.  Remember, Roubini predicted the financial crisis (an incredible feat for a Keynesian), Greece's inevitable default, and, most importantly, the setting up of Dominique Strauss-Kahn in Manhattan.  The man has more ties to the government than the head of an organized crime syndicate.  Probably even more than Goldman Sachs.  If Netanyahu does actually attack Iran in September, it is a virtual guarantee that we will back him, no question.  The real question is how much longer Americans will put up with wars that have nothing to do with us.

Minggu, 17 Juli 2011

Thomas Friedman and the Upcoming Generation Clash, Citigroup Hiring Like Crazy, and Jefferson County Alabama Ready to Default?

Thomas Friedman, never the brightest guy when it comes to economics, has a pretty damn good column in the New York Times today highlighting the upcoming generational clash:
Indeed, if there is one sentiment that unites the crises in Europe and America it is a powerful sense of “baby boomers behaving badly” — a powerful sense that the generation that came of age in the last 50 years, my generation, will be remembered most for the incredible bounty and freedom it received from its parents and the incredible debt burden and constraints it left on its kids. 
Class warfare eat your heart out, this will be the war that challenges the status quo of how industrialized countries are governed.  Friedman skips the b/s and gets at the core of the issue.  The generation preceding mine was given lavish entitlements by the generation before and accumulated so much debt that the whole financial industry is literally built upon a fake sense of prosperity.  What Friedman leaves out however is that this mindset has been ingrained in my generation for the most part as many of my peers, not idiots by any means, still don't see the writing on the wall.  The entitlements programs our parents have grown dependent on (if you don't believe me, check out the myriad of polls and studies that show Americans don't save nearly enough for retirement) have also served to ingrain a sense of entitlement in my generation.  Go to any college campus and ask students there if they have "rights' to such things as health care, education, or even water. I bet $100 the majority of kids will say yes to all three.

If you wanna see just how outta control things have gotten, see the following three graphs:
Not to worry though, NYT's token conservative (which is basically a Democrat who likes war mongering) David Brooks prescribes his own solution to curtailing all those expensive end of life treatments: pull the plug!
The fiscal implications are all around. A large share of our health care spending is devoted to ill patients in the last phases of life. This sort of spending is growing fast. Americans spent $91 billion caring for Alzheimer’s patients in 2005. By 2015, according to Callahan and Nuland, the cost of Alzheimer’s will rise to $189 billion and by 2050 it is projected to rise to $1 trillion annually — double what Medicare costs right now.
Obviously, we are never going to cut off Alzheimer’s patients and leave them out on a hillside. We are never coercively going to give up on the old and ailing. But it is hard to see us reducing health care inflation seriously unless people and their families are willing to do what Clendinen is doing — confront death and their obligations to the living.
Brooks basically ends up advocating for a central authority to deny care to the elderly.  No surprise there.

With all the Fed money printing starting to seep its way into the system, this shouldn't be a surprise either:
For 2 1/2 years, Vikram Pandit was forced to hunker down to fix Citigroup's troubled businesses and fend off the bank's critics in Washington.
Now, after reporting a 24 percent profit increase for the second quarter, Pandit, Citi's chief executive, is starting to play offense.
Citigroup has been hiring dozens of investment bankers, dialing up advertising and drawing up plans to add several hundred branches worldwide, including more than 200 in major cities across the United States. The bank is in the middle of stitching together its disparate technology systems - a mammoth effort known internally as Project Rainbow - and spending more than $1 billion a year to keep up its prized global transaction services franchise.
There you go folks, Citigroup is expanding from the benefit of Bernanke's printing press.  This goes along with Silicon Valley, which makes sense if banks like Citigroup are improving their technology infrastructure.

So Meredith Whitney's prediction of multiple municipal bankruptcies may finally be coming to fruition:
(Reuters) - Bankruptcy is still a "very strong possibility" for Alabama's Jefferson County, Governor Robert Bentley said on Saturday -- a move that could make for the largest municipal bankruptcy in U.S. history.
A $3.2 billion bond debt related to Jefferson County's sewer system has pushed the county toward the brink, and a rare Chapter 9 municipal bankruptcy could have ripple effects in the $2.9 trillion U.S. municipal bond market.
If I am lucky, I will have an article in the Press and Journal this week highlighting the similarities between Greece and perhaps the next biggest municipal bankruptcy, the great city of Harrisburg, Pennsylvania.

Sabtu, 16 Juli 2011

WSJ Interview with Jim Grant, New Adjusted CPI Numbers Out, and Ron Paul Holds Another Record

For a great weekend read, check out Jim Grant's interview with Holman Jenkins in the Wall Street Journal.  The interview doubles as a kind of autobiography and critique of Grant's favorite institution, the Federal Reserve and Wall Street.  Here are some excerpts:
The "fiat" dollar, he adds ruefully, "is one of the world's astounding monetary creations. That a currency of no intrinsic value is accepted as money the world over is an achievement that no monetary economist up until not so many decades ago could have imagined. It'll be 40 years next month that the dollar has been purely faith-based. I don't believe for a moment it's destined to go on much longer. I think the existing monetary arrangements are so precarious, so ill-founded and so destructive of the economic activity they are supposed to support and nurture, that they will be replaced by something better." 
Earlier this year Mr. Grant put his mouth where his mouth is, testifying before Rep. Ron Paul's House monetary affairs subcommittee on the virtues of the gold standard. No Democrats and few Republicans showed up. Asked to predict exactly when the dollar will blow up, Mr. Grant jokes, "I'd say 1978."
But his point is an earnest one and brings us back to the modern character of Wall Street. The gold standard, he says, citing the "late, great" libertarian economist Murray Rothbard, was the "people's system. If you didn't like the currency, you could exchange your paper for gold and that sent a message."
In our age of "wiki everything," Mr. Grant finds it anomalous that we sacrifice freedom of monetary choice for the diktats of central planners acting out of the Fed's faux-colonnaded headquarters in D.C. The fiat dollar is an "elite" system, he says, and Wall Street is its supporting "interest group"—those nimble, market-savvy, plugged-in folks know how to shuffle assets and exploit cheap funding from the Fed to leverage up their profits and soften the downside.
"Wall Street today is a statist creation," adds the man who has known, loved and chided the Street for nearly four decades as one of its most able observers. "Greenwich, Connecticut"—where billionaire hedge-fund operators keep their homes—"is not what Fifth Avenue was in the Edwardian age. Greenwich, Connecticut will be the last to sign up for the new gold standard."
How such truth made it into the Wall Street Journal is shocking.  I am always amused by the people I argue with on the Huffington Post who actually think that Wall Street is a complete free market enterprise not given so many privileges by our great Congressional leaders.  Republicans are of course the only political party beholden to Wall Street and Democrats are forever the great fighters for the middle class, that idea will never change in their minds.

The latest CPI data is out today and while headline inflation is expectantly down, but core CPI is slightly rising.  As Robert Wenzel points out, Krugman is beside himself with this revelation and wants a new measure of core inflation that excludes those dastardly food and energy prices.  It's a good thing that consumers don't buy such things as food or energy a lot right?  Seriously though, for someone like Krugman who constantly claims to be looking out for the lower and middle class, I am always dumbfounded that he would opt for inflation in all circumstances which benefits the elite banking class first.  This even more so since Krugman seems to believe he disproves supply side economics with every blog post.

As the numbers continue to be tallied for which GOP contender for president raised the most money, Ron Paul has nabbed the #2 spot earning more than any other candidate besides Mr. Bankster's choice himself Mitt Romney.  Besides this impressive feat, another record for Ron Paul was released today:
This week, we learned that GOP Presidential Candidate Ron Paul is the only congressman to -- ever -- hit a home run over the fence during an annual "Congressional Baseball Game."
Now if he could only take that bat to the Fed we would be in way better shape.

Update- Wow, kudos to Jeffery Snider, President of Atlantic Capital Management, for his wonderful RealClearMarkets article on the Federal Reserve's attempt at creating the illusion of prosperity and wealth.  Without naming the Austrian Business Cycle Theory, Snider lays out the fundamentals of how the Fed distorts the business cycle with easy credit policies:
In a way, central banks are engaged in nothing more than a modified "pump and dump". They are attempting to create the illusion of value through price action. By maintaining high valuations due almost solely to their own purchases, they hope to "attract" additional investors into the process. Whereas the exit plan of the traditional version seeks a higher price to disgorge the schemer's original holdings, the legal, central bank version is trying to buy public faith in order to disgorge a larger acceptance of a return to normalcy. In both cases, the public gets abused - suckered investors in the first, taxpayers in the second.
It does not matter if the ECB buys a substantial portion at par; the larger system is not fooled into blindly believing in scarcity, or that price action equals true value. The marketplace will instead buy on the foolishness and irresponsibility of the central bank, buying up all Greek debt solely on the ability to pawn it off on taxpayers at an unearned profit. But even here, it only works as far as faith in the ECB and the euro is maintained, since value has not really changed. The central bank interference is nothing more than a game of musical chairs, with risk investors willing to play as long as they believe the music will keep playing. The second the music stops, that entire intervention and managed price discovery becomes irrelevant as the assets suddenly become bidless.
Snider even takes a shot at F.D.R.:
You may not be able to eat gold, but it is a constant reminder of the constraints that it places, even in our modern times, on central bankers - earning their scorn and pejorative dismissal. There is a reason that Americans' private gold holdings were confiscated by executive decree in 1933; they offered actual protection against the currency devaluation that was being planned. Gold is the foil, the opt-out, of every central bank confidence scheme.
The whole article is highly recommended and serves as a great beginner's essay for those looking to learn the ABCT.

Jumat, 15 Juli 2011

Jim Rogers on the Debt Ceiling and Upcoming Raw Deal, Rick Santelli Tells It Like It Is on Spending Cuts, and Miller and Coors Soon to Leave Minnesota?

The impeccable Jim Rogers is out with a great interview with RT.com in which he talks about what I have been bitching about for a few days now: Why the hell did Moody's wait so long to downgrade the U.S. credit rating?
"The U.S. rating should have been downgraded years ago.  I don't know why they are just now getting around to it but we know that the rating agencies don't have much of a clue about anything.  They got everything wrong in subprime.  They got everything wrong for a long time.  I don't know why they don't understand what's going on."
There it is in simple language folks.  Moody's is a joke, they just downgraded 7 Portuguese banks today and act like they are pointing out things nobody knows already.  At least one rating agency, which happens to be independent of course, gets it right:
JUPITER, Florida (July 15, 2011) — Weiss Ratings, an independent rating agency of U.S. financial institutions and sovereign debts, has downgraded the debt of the United States government from C to C-minus.
Here is another Jim Rogers interview with Fox Business from a few days ago discussing the debt ceiling:
"They will probably raise the debt ceiling and announce some kind of wonderful deal, which they will then promptly ignore just as they did the Gramm-Rudman.  The United States is not going to close down. It might be good for the world if the United States government closed down for a while but I can not see that happening.  Something will happen, things will get better, but then in 6 months or a year we will be worse again.
Mark the man's words, he is a legend for a reason.

Speaking of legends, Rick Santelli is back actually calling for a U.S. default on CNBC while also calling out Barney Frank and the BLS creation of fake jobs through the birth/death formula.
And of course Santelli asks the big question on cutting spending that none of the children in Congress want to answer:
If not now, when?! If not now, when!? If not now, when?!
Though the Minnesota state government shutdown seems to be coming to end, the real reason behind the solution may have been revealed:
The state shutdown means Miller-Coors will have to stop selling beer in Minnesota. State officials have told the company it must come up with a plan to remove its 39 brands of beer from shelves, and bars in a matter of days.
The company failed to renew its brand license with the state before the shutdown. Each alcohol brand needs to pay a $30 brand license fee, which is good for three years.
Without the license Miller-Coors cannot sell beer in the state.
I guess the martini lovers in Minnesota's General Assembly are outflanked by beer lovers. Still, the fact that Minnesota, and most states I imagine, have laws like that is idiotic beyond words.  Why not just have a bureaucrat hold the can/bottle up to my mouth when I wanna drink?  Think of all the jobs that will be created!  Paul Krugman and Brad Delong are probably fidgeting with excitement over that type of idea with job creation and social engineering rolled into one.

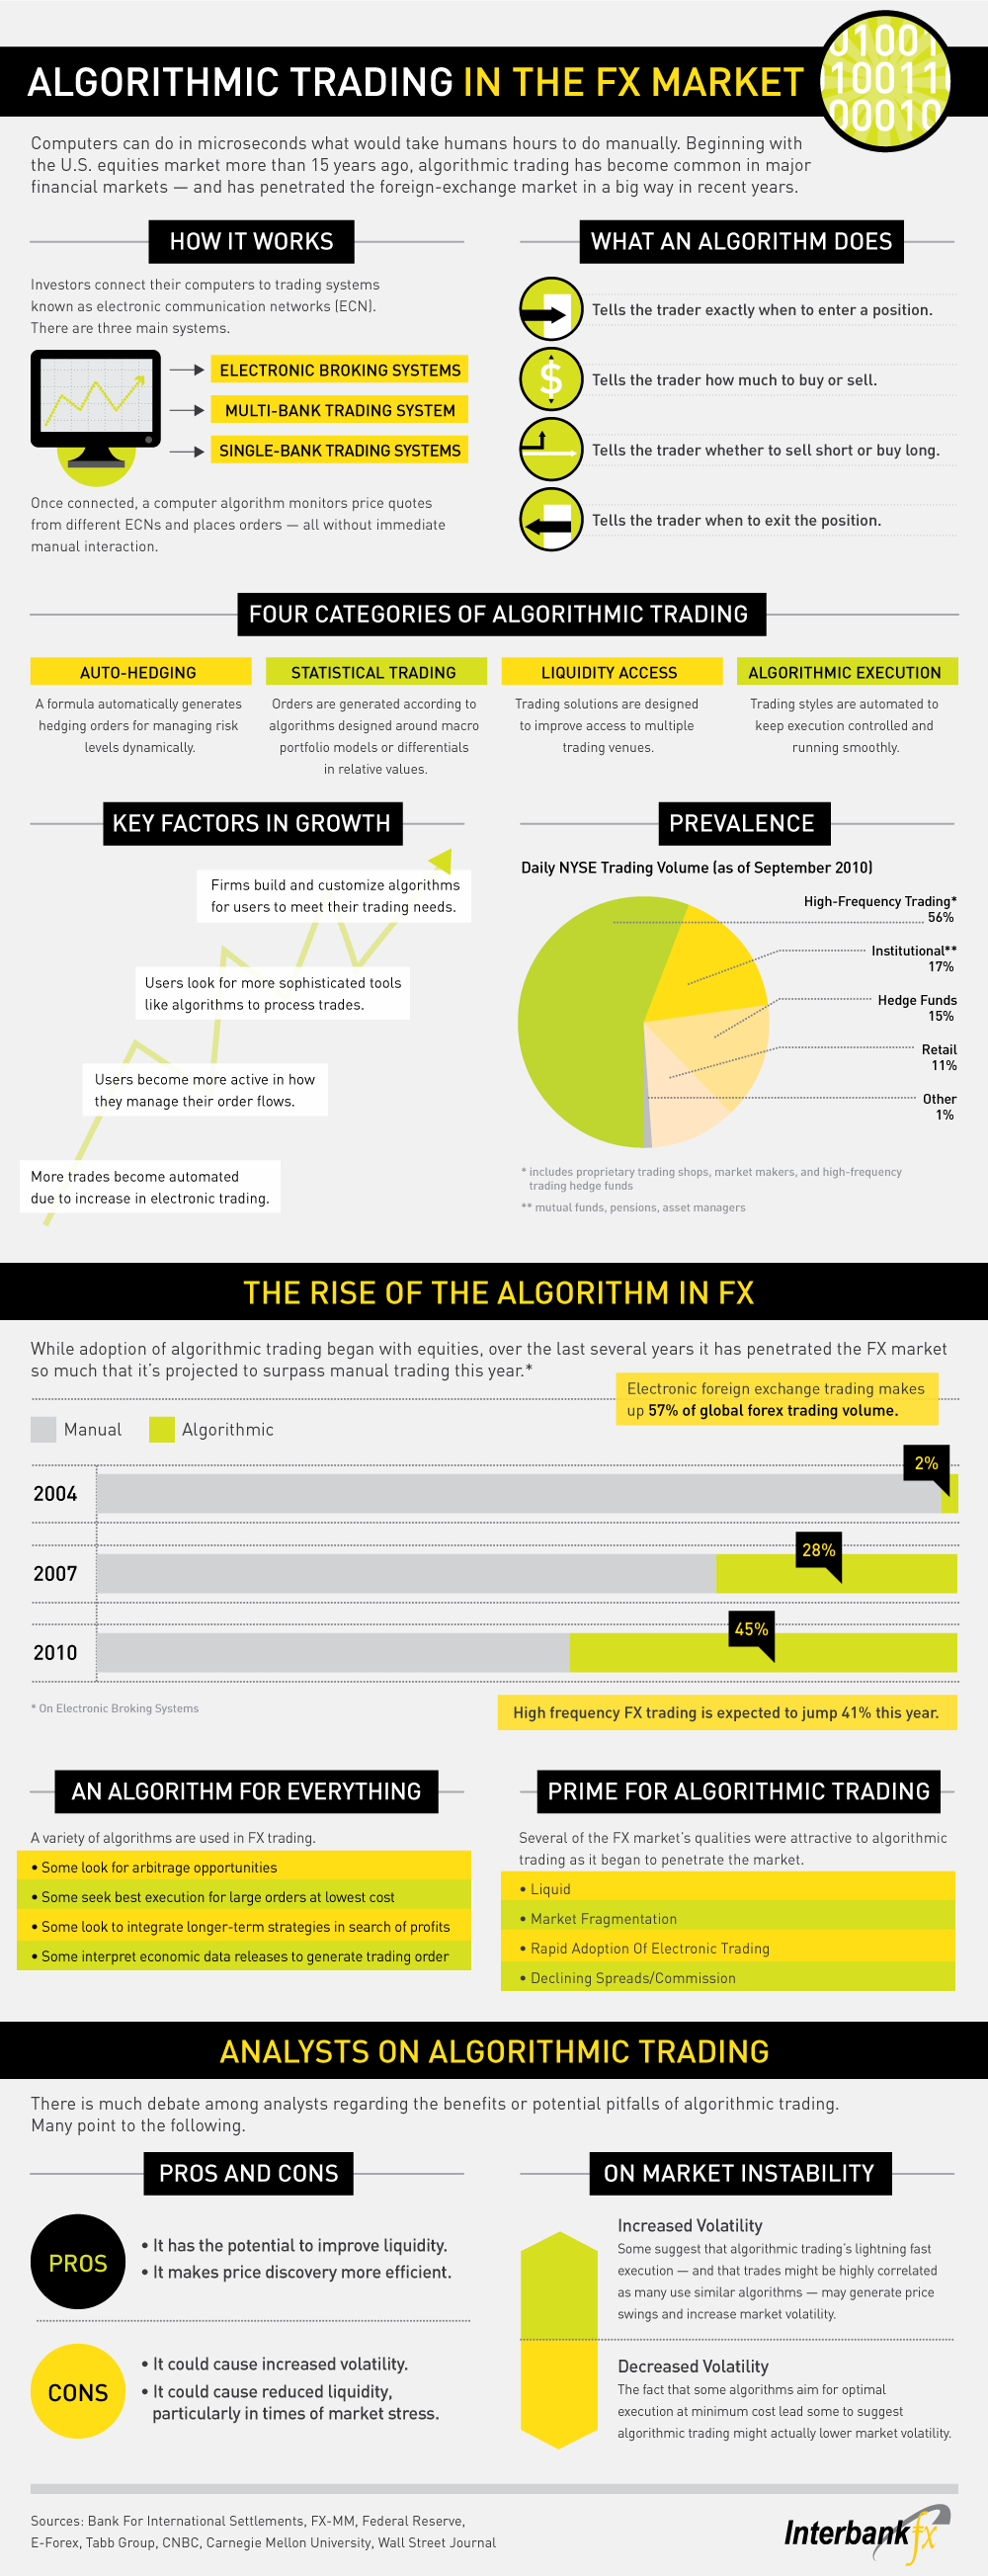
I will end with a very simple and straightforward chart on how prominent algorithms are in modern trading
Oh and here is Ron Paul first, but hopefully not last, campaign video:
This may only be a taste of what's to come.

Kamis, 14 Juli 2011

Ron Paul Says AAA Rating Not Worth Saving, Interactive Map of Income Distribution in the World, and Deadliest 6 Months for Civilians in Afghanistan

Like I have continued to say, the big 3 credit rating agencies are garbage when it comes to making accurate credit ratings when it matters.  Ron Paul agrees with me today on Bloomberg:


Paul on whether the AAA rating is worth saving:

"Probably not. I think if you had a market evaluation on this issue, it should have marked down a long time ago. I always wonder about these ratings. Bond ratings before the crash three years ago were not very helpful. Sometimes I wonder whether this is more of a political theater to build up the fear. First, we won't be able to write the checks for Social Security and the next thing there'll be a down rating of bonds."

"The market does the final rating. I think our solvency in our dollar is better rated by the price of gold rather than what Moody's will say. In the short run, what Moody's does will have an effect."
We are technically insolvent as far as paying our liabilities long term goes, yet we continue to have a AAA rating.  Hence the need to not trust what the big rating agencies say.

National Geographic has a very interesting map on income distribution in the world, click on it below to go to the interactive part:
At the very least, the picture is aesthetically pleasing.

Our wonderful Commander in Chief who also was a recipient of the Nobel Peace Prize has another record to be proud of:
The first six months of 2011 were the deadliest for civilians in Afghanistan since the war began in 2001, a UN report has found.
The country saw 1,462 civilian deaths in January to June, a 15% increase on the same period last year.
And yet liberals won't support the one anti-war candidate running for president because of the R next to his name. 

Rabu, 13 Juli 2011

Ron Paul Vs. Ben Bernanke, Moody's Puts the U.S. AAA Credit Rating on a Downgrade Review, and Somlia CIA Prisons

The blogosphere was all a twitter today as Ron Paul and Ben Bernanke squared off in probably one of the last times in the House Financial Services Committee today.  Right from the get go, WSJ reports on this golden nugget:
Ron Paul‘s announcement yesterday that he won’t seek re-election in 2012 elicited the expected reaction from Federal Reserve Chairman Ben Bernanke: a big smile.
As today’s House hearing got underway, frequent Fed critic Paul prepared to give his opening statement. But before he could speak, Rep. Barney Frank (D., Mass.) brought up the announcement, saying that despite their disagreements he would miss the Texas Republican.
Paul thanked him for the sentiment and noted some were saying the announcement would likely bring a smile to the Fed chairman’s face. Bernanke obliged, and was clearly trying to maintain a polite grin.
In the preliminary testimony, Bernanke once again made it clear that if the economy continues to be sluggish, he will be more than willing to suck up some more Treasury bonds:
Federal Reserve Chairman Ben S. Bernanke told Congress the central bank is prepared to take additional action, including buying more government bonds, if the economy appears to be in danger of stalling.
My boss at my old internship, though fairly liberal, told me once that although he thinks an institution such as the Fed should be around to have some control over the economy (I tried for four months to convince him otherwise, but you know how some people are), that idea that one man can affect global markets with the simple utterance of a few words is downright scary.  Today demonstrated just how right he was.  As Bernanke testified today, the dollar weakened while gold soared to brand new heights:
The dollar weakened against all its most-traded counterparts as Federal Reserve Chairman Ben S. Bernanke said policy makers will provide economic stimulus if needed and investor demand for higher-yielding assets increased.
Gold futures surged to a record $1,588.90 an ounce as the dollar’s slump and the European debt crisis spurred demand for precious metals as alternative assets. Silver surged the most since March 2009.
It's a shame Bernanke comes off as rather timid interviews, any other narcissist in Congress or Washington would more than love to have that kind of power.

So what did Ron Paul say today which caused quite a stir?  A rather simple question really:

Is gold money?
(skip to just before the 5:00 mark)
Bernanke pause is almost deafening.  He knows damn well what Paul is getting at.  Now "no" may be the technical answer in terms of currency, but Paul asked about money, not currency.  Sure, gold isn't legal tender now.  But Bernanke's complete disregard to gold's use for thousands of years was just plain sloppy.  He played right into Paul's diamond question and his answer of "traditional" is bullshit considering how much gold China's Central Bank has been purchasing.  Also, watch the video just before the "is gold money?" exchange, Bernanke claims gold is used to hedge against world uncertainties and disasters.  Hmmm, I don't think people buy gold in preparation of global warming or natural disasters, what could they possibly buy gold for......
Bernanke sure knows how to be slick.

The debt ceiling negotiations continued today and don't seem to be getting there.  In another worthless attempt at gaining credibility, Moody's had this to say:
New York, July 13, 2011 -- Moody's Investors Service has placed the Aaa bond rating of the government of the United States on review for possible downgrade given the rising possibility that the statutory debt limit will not be raised on a timely basis, leading to a default on US Treasury debt obligations. On June 2, Moody's had announced that a rating review would be likely in mid July unless there was meaningful progress in negotiations to raise the debt limit.
Once again, if Moody's (or S&P or Fitch) had any credibility, it would have downgraded the U.S.'s credit rating a long time ago.

The Nation, not one of my favorite rags, has a pretty good article on CIA prisons in Somalia today:
As part of its expanding counterterrorism program in Somalia, the CIA also uses a secret prison buried in the basement of Somalia’s National Security Agency (NSA) headquarters, where prisoners suspected of being Shabab members or of having links to the group are held. Some of the prisoners have been snatched off the streets of Kenya and rendered by plane to Mogadishu. While the underground prison is officially run by the Somali NSA, US intelligence personnel pay the salaries of intelligence agents and also directly interrogate prisoners. The existence of both facilities and the CIA role was uncovered by The Nation during an extensive on-the-ground investigation in Mogadishu. Among the sources who provided information for this story are senior Somali intelligence officials; senior members of Somalia’s Transitional Federal Government (TFG); former prisoners held at the underground prison; and several well-connected Somali analysts and militia leaders, some of whom have worked with US agents, including those from the CIA. A US official, who confirmed the existence of both sites, told The Nation, “It makes complete sense to have a strong counterterrorism partnership” with the Somali government.
According to former detainees, the underground prison, which is staffed by Somali guards, consists of a long corridor lined with filthy small cells infested with bedbugs and mosquitoes. One said that when he arrived in February, he saw two white men wearing military boots, combat trousers, gray tucked-in shirts and black sunglasses. The former prisoners described the cells as windowless and the air thick, moist and disgusting. Prisoners, they said, are not allowed outside. Many have developed rashes and scratch themselves incessantly. Some have been detained for a year or more. According to one former prisoner, inmates who had been there for long periods would pace around constantly, while others leaned against walls rocking.
The article is pretty long, but The Nation should be commended for uncovering some important facts about our illegal detainment of foreigners.  Still, I don't see The Nation coming out anytime soon calling for Obama to be put on trial for war crimes.