Senin, 25 Juli 2011

Self Reference for Monetary Base

This is just a self reference for myself, here is the link to the Fed's official monetary base increases.  It's disturbing what the latest says:
Percent change at seasonally adjusted annual rates   M1         M2
------------------------------------------------------------------
3 Months from Mar. 2011 TO June 2011 12.5 8.2
6 Months from Dec. 2010 TO June 2011 13.0 6.8
12 Months from June 2010 TO June 2011 13.0 6.0

The Case for a Gold Standard, More SEC Revolving Door, 24 Types of Libertarians, and Ghost of Rothbard Haunting Bernanke?

For a little bit of educational entertainment, check out this nice little video on why we should return to the gold standard:
There is a conflict of issue in this video since it has been put out by Gold Resource Group, but regardless the overall message is correct.  Fiat funny money finances poverty-perpetuating welfare programs and war-mongering acts of imperialism.  WWI, WWII, and the Vietnam War didn't have to be fought.  The Civil War saw the introduction of the non-gold/silver backed "greeback."  FDR confiscated gold from the public and devalued the dollar to pay for the New Deal.  Fiat money has a rich history of being used to finance the  ever growing U.S. government and has been simultaneously used to benefit Wall Street and the banksters for nearly a century.  Why the left trust the government with the money despite this mounting evidence is beyond me.

The same kind of leftist blind faith can be applied to government regulators as well.  Check out this aptly titled article "The SEC's Revolving Door" from the Project on Government Oversight:
If you’re looking for evidence of the revolving door that spins between the federal government and Wall Street, look no further than Daniel Gallagher, President Barack Obama’s recently announced nominee for Securities and Exchange Commission commissioner.
Gallagher certainly appears qualified for the job. He previously worked at the SEC as a counsel to then-Chairman Christopher Cox, and later played a key role in organizing the SEC’s response to the financial crisis. Yet Obama’s nomination of Gallagher to help lead the agency during a critical time in its history is also the latest example of the agency’s coziness to the industry it oversees.
Gallagher is currently a partner at WilmerHale. The pricey law firm’s high-profile clients have included Goldman Sachs, JPMorgan Chase, Citigroup and other Wall Street giants regulated by the SEC. If the Senate confirms him, this would be Gallagher’s second spin through the revolving door — he previously left WilmerHale to join the SEC in January 2006, only to return to the firm in 2010. And he would be the latest on an ever-expanding list of WilmerHale alumni at the SEC, including the current general counsel, deputy general counsel, associate general counsel, corporation finance division director, enforcement division chief counsel and deputy secretary.
Of course, the revolving door spins in both directions. Many former SEC employees leave the agency to join WilmerHale and other legal, accounting and consulting firms that represent clients in the securities industry. Several recent reports by the SEC Inspector General have raised troubling questions about whether the promise of future employment representing Wall Street causes some SEC officials to treat potential employers and their clients with a lighter touch.
So what's the sum of all this SEC revolving door action:
All told, POGO’s database shows that 219 former SEC employees filed 789 statements between 2006 and 2010 announcing their intent to appear before the SEC or communicate with its staff on behalf of private clients. One former employee had to file 20 statements during this time period in order to disclose all his clients and the issues on which he expected to appear before the SEC. Another former employee filed his first statement just two days after leaving the agency.
Well this must be baffling for all the Paul Krugman and Robert Reich's out there who seem to think angles work at the federal government.  Don't worry though, as long as Barney Frank keeps writing regulatory bills, that should put an end to financial crisis.  Remember now, Barney Frank clearly saw the 2008 financial crisis coming and warned the public about the insolvency of Fannie Mae and Freddie Mac...

Well even as a libertarian, you gotta have a sense of humor about yourself.  With that in mind, it's always nice to be acknowledged:
Someone special told me I was the "more libertarian than thou" type, I figured I was more the "atlas" type.

Now for the most idiotic comment of the day from W.W. at The Economist:
Although sophisticated Austrian-school monetary economists such as George Selgin and Larry White defend rule-based inflation-targeting policies not all that different from Mr Sumner's neo-monetarist nominal GDP-targeting rule, the ghost of Murray Rothbard looms much larger on the free-market right.
Are you freaking kidding me?  Who the hell besides Ron and Rand Paul still promote Rothbardian monetary policy to a mainstream audience.  Sure Robert P. Murphy and Tom Woods make the occasional appearance on Freedom Watch, but does this guy seriously think that when Bernanke turns the printing presses on he thinks WWRD (What Would Rothbard Do?)?  Even after making a statement like that, W.W. attempts to correct himself:
Now, I don't claim that the right, loosely defined, is chock full of Murray Rothbard fanatics. And whatever it is that is keeping Ben Bernanke's Fed from loosening up, it's not the enduring intellectual legacy of Murray Rothbard. At least, not directly. But I do believe elements of Ron Paul's Rothbardian monetary philosophy enjoy a great deal of currency on the grassroots right, and I believe this exerts a considerable gravitational force on the institutional right, such that arguments for zero or very low inflation are accorded more weight than they would were Milton Friedman still in full effect.
At this point he may be right in that many tea partiers (by grassroots right, I assume this is what he is talking about) hardly even know who Rothbard was, but if Rothbard did indeed still have a lasting mainstream impression, we would not have seen the huge expansion of the monetary base that proceeded the financial crisis that we did.  As much as I would love to believe that Rothbard has a huge amount of influence on everyone else as he has had on me, that is simply wishful thinking.
I will end with another great video interview with Jim Rogers who, though not saying anything new, continues to stay on point: don't trust the rating agencies, the U.S. is bankrupt, and the debt ceiling fiasco is a sham:

Minggu, 24 Juli 2011

Rumors of "Super Congress," Fitch States the Obvious, and China Property Bubble Ready to Burst

While the debt ceiling theater continues, you must continue to be weary of any tricks that get slid into what will most likely be hailed as an extraordinary compromise.  Check out this insidious proposal via HuffPost:
WASHINGTON -- Debt ceiling negotiators think they've hit on a solution to address the debt ceiling impasse and the public's unwillingness to let go of benefits such as Medicare and Social Security that have been earned over a lifetime of work: Create a new Congress.
This "Super Congress," composed of members of both chambers and both parties, isn't mentioned anywhere in the Constitution, but would be granted extraordinary new powers. Under a plan put forth by Senate Minority Leader Mitch McConnell (R-Ky.) and his counterpart Majority Leader Harry Reid (D-Nev.), legislation to lift the debt ceiling would be accompanied by the creation of a 12-member panel made up of 12 lawmakers -- six from each chamber and six from each party.
Legislation approved by the Super Congress -- which some on Capitol Hill are calling the "super committee" -- would then be fast-tracked through both chambers, where it couldn't be amended by simple, regular lawmakers, who'd have the ability only to cast an up or down vote. With the weight of both leaderships behind it, a product originated by the Super Congress would have a strong chance of moving through the little Congress and quickly becoming law.
Unbelievable.  This so called "Super Congress" is so blatantly unconstitutional it will probably be created and approved of by the Supreme Court.  This "Super Congress" will be such a centralization of power, it will have an incredibly detrimental effect on passing liberty-vanquishing legislation.  And by detrimental, I mean it will make passing such legislation easier and quicker.  It will be the complete corruption of the slow-moving legislative system the founders of this country developed.

Essentially, a "Super Congress" will be the equivalent of hocking a luggie on James Madison's grave.

Moving over to Greece now, the obvious is finally official:
(Reuters) - Fitch ratings agency declared Greece would be in temporary default as the result of a second bailout, which Athens said had bought it breathing space. 
Of course a temporary default isn't as good as a real default so the fiscal can will continue to be kicked down the road.

Greece may be a disaster waiting to happen, but China's inhouse disaster seems to be finally unfolding:
So you thought that UK housing was unaffordable. Try Beijing and Shanghai, where as can be seen from the graphic below, prices are off the scale relative to income, the commonly used yardstick for measuring affordability. OK, so these are the boom cities of the Chinese economic miracle, but even on a nationwide basis, affordability is no lower than in the UK.
china-housing-bubble-graphi
Little noticed amid the furore of the euro crisis, HSBC’S preliminary survey of China’s factories, published this week, indicated manufacturing activity in the world’s second-biggest economy actually declined in July from the month before, the first such contraction in a year. The HSBC purchasing managers index for China has been falling for months now, indicating a protracted fall off in growth as the Chinese authorities act to rein in rampant inflation.
Now we all get to see if the world economy can handle a slowing China.  My guess is no, but Fed money printing in the U.S. is starting to hit the system.  Whether it will be enough to offset China's slowing down will remain to be seen.

I will end by linking to this great graphic on how the banks in the U.S. are regulated from the Fiscal Times:

Sabtu, 23 Juli 2011

Pirate Entrepreneurship, Oversight Blocked on Mercenary Army in Iraq, and Jim Grant Reviews New Bastiat Collection

Wow, check out this profile of Max Hardberger in the Telegraph yesterday:
Hardberger is a 62-year-old adventurer from Louisiana who specialises in stealing back ships that have been fraudulently seized in corrupt ports, mostly in Latin America and the Caribbean.
He describes himself as a 'vessel repossession specialist’, a kind of maritime repo man who ghosts into tropical hellhole ports, outwits the guards and authorities, and ghosts out again with a 5,000- or 10,000-ton cargo ship, usually under cover of darkness and preferably during a heavy rainstorm.
Whether it’s good or not depends on your perspective. For his clients he is a godsend, well worth the $100,000-plus that he charges to retrieve a ship. To foreign port authorities, judges, coastguards, naval commanders and government officials, he is a flagrant and notorious law-breaker, and if they ever manage to catch him at it, he can expect a long sentence in a vile prison.
In a world lacking a competitive, market based justice system, Harberger opts for taking justice in his own hands for his clients.  This business is apparently fruitful enough for him to do it though it comes with quite a bit of danger.  While the U.S. justice system is not as corrupt as those of Latin America countries, government officials will never be above the level of taking bribes.  What Harberger is doing is true justice for those who have lost their possession even though another government may have designated a ship to be the property of someone else.  It is a testament to the corruptibility of modern governments and the market ingenuity of those looking to be paid for correcting injustices.  Speaking of ingenuity:
The desperate ship owner may then decide to call Hardberger, or more precisely his company Vessel Extractions, LLC, based in New Orleans. 'The first phase is for me to get my expenses and go into the port to do my research. I either keep a very low profile, or I hire the youngest prostitute I can find and pretend to be a drunken old American ship captain who has gone native with a teenage girlfriend. There’s one in every port so people see me in that role and they don’t look past it, and I can look around and ask questions without attracting attention.’
Prostitutes, in fact, are a key resource for Hardberger. 'I don’t consort with them and I’m one of the few seamen I know who never has,’ he says. 'But I’ll send them on board to gather information, or entice the guards away from the ship. I’ll give them a bottle of rum that I’ve mixed with crushed-up sleeping pills and tell them to start pouring drinks. It goes without saying that most prostitutes are excellent actresses, and I’ve found them extremely useful.’
Since I am on the topic of government corruption, see the latest example of the rampant corruption that embodies and profits from our foreign policy via Wired:
By January 2012, the State Department will do something it’s never done before: command a mercenary army the size of a heavy combat brigade. That’s the plan to provide security for its diplomats in Iraq once the U.S. military withdraws. And no one outside State knows anything more, as the department has gone to war with its independent government watchdog to keep its plan a secret. Stuart Bowen, the Special Inspector General for Iraq Reconstruction (SIGIR), is essentially in the dark about one of the most complex and dangerous endeavors the State Department has ever undertaken, one with huge implications for the future of the United States in Iraq. “Our audit of the program is making no progress,” Bowen tells Danger Room.
For months, Bowen’s team has tried to get basic information out of the State Department about how it will command its assembled army of about 5,500 private security contractors. How many State contracting officials will oversee how many hired guns? What are the rules of engagement for the guards? What’s the system for reporting a security danger, and for directing the guards’ response?
And for months, the State Department’s management chief, former Ambassador Patrick Kennedy, has given Bowen a clear response: That’s not your jurisdiction.
Look for President Obama to run on drawing troops out of Iraq but fail to mention that mercenary armies will still be there.  Our presence in Iraq is not going to end anytime soon.  Meanwhile, the war profiteering will continue.

Jim Grant has a great Wall Street Journal book review on a collection of Frederic Bastiat's writings in English for the first time entitled "The Man and Statesman."  Right off the bat, Grant leads with a classic Bastiat line:
Because nobody else can understand them, modern economists speak to one another. They gossip in algebra and remonstrate in differential calculus. And when the pungently correct mathematical equation doesn't occur to them, they awkwardly fall back on the English language, like a middle-aged American trying to remember his high-school Spanish. The economist Frédéric Bastiat, who lived in the first half of the 19th century, wrote in French, not symbols. But his words—forceful, clear and witty—live to this day.
It is always surprising to see how similar Bastiat's writing over 100 years ago are to the troubles we go through today.  Bastiat's writings have made huge impacts, but we still have a long way to go before they are fully adhered to.  The most interesting part of the review is Grant's mentioning of Democratic congressmen mentioning Bastiat in order criticize tariff legislation by the GOP.  If only those Congressmen would use Bastiat's stunning critiques to analyze their own idiotic positions.  Overall, Gran'ts review is highly recommended.

Jumat, 22 Juli 2011

Ron Paul's Great Bloomberg Op-Ed, Rasmussen Reporting Obama 41% Paul 37%, and Here Comes the European Monetary Fund!

Quick post today, spent a total of 7 hours driving back and forth to New York.  While the big news of the day seems to be Speaker Boehner pulling an Obama and walking out of the debt ceiling negotiations and some nationalist douche blowing up a bomb in center of Oslo, Norway, Ron Paul has a fantastic editorial in Bloomberg today that outlines exactly what America needs to hear:
Unless major changes are made today, the U.S. will default on its debt sooner or later, and it is certainly preferable that it be sooner rather than later.
If the government defaults on its debt now, the consequences undoubtedly will be painful in the short term. The loss of its AAA rating will raise the cost of issuing new debt, but this is not altogether a bad thing. Higher borrowing costs will ensure that the government cannot continue the same old spending policies. Budgets will have to be brought into balance (as the cost of servicing debt will be so expensive as to preclude future debt financing of government operations), so hopefully, in the long term, the government will return to sound financial footing.
And of course Paul shatters the ridiculous notion that the U.S. has never defaulted on its debt before:
The U.S. government defaulted at least three times on its obligations during the 20th century.
-- In 1934, the government banned ownership of gold and eliminated the right to exchange gold certificates for gold coins. It then immediately revalued gold from $20.67 per troy ounce to $35, thus devaluing the dollar holdings of all Americans by 40 percent.
-- From 1934 to 1968, the federal government continued to issue and redeem silver certificates, notes that circulated as legal tender that could be redeemed for silver coins or silver bars. In 1968, Congress unilaterally reneged on this obligation, too.
-- From 1934 to 1971, foreign governments were permitted by the U.S. government to exchange their dollars for gold through the gold window. In 1971, President Richard Nixon severed this final link between the dollar and gold by closing the gold window, thus in effect defaulting once again on a debt obligation of the U.S. government.
And what would a Ron Paul op-ed be without mentioning the Austrian school:
The Austrian School’s theory of the business cycle describes how loose central bank monetary policy causes booms and busts: It drives down interest rates below the market rate, lowering the cost of borrowing; encourages malinvestment; and causes economic miscalculation as resources are diverted from the highest value use as reflected in true consumer preferences. Loose monetary policy caused the dot-com bubble and the housing bubble, and now is causing the government debt bubble.
For far too long, the Federal Reserve’s monetary policy and quantitative easing have kept interest rates artificially low, enabling the government to drastically increase its spending by funding its profligacy through new debt whose service costs were lower than they otherwise would have been.
So if you have been paying attention at all to major news networks, you would see that Paul is getting a lot of coverage lately.  Certainly a lot more than last election cycle.  Well it looks like its finally beginning to pay off, check out the title of this article from the Neo-Con poll lovers group known as Rasmussen:
"Obama 41%, Ron Paul 37%"
The latest Rasmussen Reports national telephone survey of Likely Voters shows Paul picking up 37% of the vote, while the president earns 41%. The Texas congressman joins Mitt Romney, Michelle Bachmann, and Rick Perry as candidates within hailing distance of the president at this time.
I always tell people around me that Ron Paul's real challenge will be winning the nomination from the Republican Party, not winning the general election.  If, God forbid, Paul wins the nomination, all he has to do is point out that Obama has escalated the War on Terror, increased the War on Drugs, and has generally aligned himself with the interests of Wall Street besides wanting to raise taxes on the super rich (and by super rich, he means those bourgeoisie households earning the extraordinary amount of $250,000 a year).  Once pointing these facts out, its always fun to ask Obama supporters how exactly he qualifies as a liberal again.

Yesterday, in light of the new Greece bailout, I mentioned the idea of a European fund being made to start selling bonds.  Well what do ya know:
French President Nicolas Sarkozy compared the transformation of the bailout fund to the creation of a “European Monetary Fund.”
We can only hope that this proposal doesn't get adopted but judging from recent bailout actions, it seems like a worthless endeavor.

Kamis, 21 Juli 2011

It's Official-Greece May Default (Just a Tiny Bit), More Corruption from the Fed, and Why the Gang of Six Budget Proposal is a Trap

Today's emergency (note: they are always emergencies) meeting of Euro leaders seemed to show a slight acknowledgement of the obvious: Greece needs to default:
BRUSSELS (AP) -- Eurozone leaders on Thursday agreed to a sweeping deal that will grant Greece a massive new bailout -- but likely make it the first euro country to default -- and radically reshape the currency union's rescue fund, allowing it to act pre-emptively when crises build up.
The deal resolves a political deadlock between Europe's top economic authorities over how to save Greece that had investors worried the debt crisis would spin out of control. Faced with the danger of big economies like Italy becoming unstable, the officials sought to outdo expectations at an emergency meeting in Brussels.
The eurozone countries and the International Monetary Fund will give Greece a second bailout worth euro109 billion ($155 billion), on top of the euro110 billion granted a year ago.
The deal on involving private creditors is widely expected to be considered a "selective default" by the ratings agencies, making Greece the first euro country to ever be in default -- if likely only for a short period of time.
It looks like the pissing in the wind has been reduced to a tinkle for now, but it won't last.  This bailout is just another kick down the road that is the fiscal insanity can of the Euro Zone.  Once Ireland and Portugal need a second bailout, or Italy and Spain need their first, the fireworks will really begin.  There is already speculation that the European Central Bank will start holding defaulted bonds; Central Bank manipulation at its finest.

Simon Black calls it "Print. Lie. Borrow. Deceive. Deny."

Sen. Bernie Sanders ironically calls it socialism:

The Federal Reserve had more than $1 trillion in loans out to a wide range of financial institutions during the financial crisis, according to a new audit of the central bank.
The Government Accountability Office (GAO) released its top-to-bottom audit of the Fed Thursday, opening the central bank to fresh criticism from the lawmaker that had pushed for the audit in the first place.
The GAO was directed to conduct the audit by a provision in the Dodd-Frank financial reform law pushed by liberal Sen. Bernie Sanders (I-Vt.).
He was quick to blast the Fed for its far-reaching activity during the peak of the financial crisis.
"As a result of this audit, we now know that the Federal Reserve provided more than $16 trillion in total financial assistance to some of the largest financial institutions and corporations in the United States and throughout the world," he said. "This is a clear case of socialism for the rich and rugged, you're-on-your-own individualism for everyone else."

The GAO found that the Fed awarded $659.4 million of contracts to private parties during the crisis to help facilitate those emergency moves.
Sorry Sen. Sanders, the word isn't socialism, its fascism.  I thought you were a socialist anyway?
Sen. Sanders may be an avowed socialist, but he sure knows how to tear Fed officials and their bankster beneficiaries a new one:
The Federal Reserve Bank of New York’s William C. Dudley got a waiver in 2008 to keep personal financial holdings of American International Group Inc. (AIG) after the company received a Fed rescue, a U.S. senator said.
Dudley, who was the New York Fed’s markets-group chief at the time and is now the bank’s president, is the senior New York Fed official identified in a Government Accountability Office report today as receiving the waiver, Senator Bernard Sanders, a Vermont Independent, said today in a statement. Jack Gutt, a New York Fed spokesman, declined to comment.
Inflation benefits those who receive the newly printed "wealth" first and serves as an incentive to consumer over save and robs those on a fixed income.  These reasons alone should be enough to put a check or barrier on how much Central Banks can inflate.  Thanks to Chad D. of Of Two Minds, there is another reason to discredit inflationists:
I've never seen this topic covered (not to say that it hasn't) which is of great interest to me: the nexus of the criminal justice system and the financial system, specifically the inflationary nature of our system. The criminal law books have statutes (and their associated regulations) with provisions regarding the value of property and the relative level of crime with which a person would be charged, if one violated that law. In addition, these statutes spell out the amount of fines and penalties for convictions for those crimes. The trouble is that these statutes are not indexed for inflation, so what happens is people are charged with a higher level of crime than they otherwise would have in the past, for no other reason than inflation.
Wow, can't say I ever thought of that.  It's basically the criminal punishment equivalent of what Rothbard called "bracket creep" in which inflation drove people to higher tax brackets in order to raise revenue for the federal government.

I will end with mentioning this great Investor's Business Daily editorial pointing out the flaw in the stupidly called "Gang of Six's" plan to (not) tackle the long term budget:
The "plan" Obama was praising isn't a plan at all, but a few pages of bullet points with vague concepts, promises of future cuts, and confusing, and at times contradictory, numbers.
And what details it does contain show that the gang has employed some of the most egregious budget tricks available to make the spending cuts look bigger and tax hikes smaller than they actually are.
The best example of this is the plan's tax proposal, which alternately boasts that it cuts taxes by $1.5 trillion and raises them by $1 trillion, but which more likely will result in taxes going up by more than $3 trillion.
According to the outline, the $1.5 trillion in "tax relief" is how the Congressional Budget Office would score the plan.
But what the gang conveniently leaves out is that the CBO's forecast has $4.6 trillion in tax hikes already baked into it. That's because the CBO baseline assumes all the Bush tax cuts get repealed, that every other temporary tax cut is left to expire, and that the alternative minimum tax continues to entrap millions more middle-class families each year.
Once you take that into account, the $1.5 trillion in "tax relief" turns instead into a $3.1 trillion tax increase over the next decade. (It's anyone's guess where the gang got its $1 trillion tax hike figure.)
Whatever scheme gets adopted to reach a deal on the debt ceiling, it will have this type of effect.  Spending cuts won't come, but tax increases (revenue generators is what they will be called) will.  Michale Reagan tweeted the concept perfectly:
Don’t let the liberals fool you! My dad was promised $3 in spending cuts for every dollar of new taxes. He died waiting for the $3 in cuts!
Update- Check out this awesome pic I got on the rode today:

Rabu, 20 Juli 2011

New Press and Journal Article, Interviews with Jim Grant, Doug Casey, John Taylor, How to Know When Housing Hits Its Bottom, and Bill Frezza's Ingenious Solution for Greece: Give the Spoiled Bastards Communism

I have an article in the Press and Journal this week comparing Harrisburg, Pennsylvania's fiscal situation to that of Greece.  They aren't so different if you can believe it:
BANKRUPTCY? Harrisburg suffering from its own big fat Greek debt

by James Miller

Greece is on the brink of bankruptcy.

Political leaders have left the country drowning in millions of euros in debt.

The European Union Fund and International Monetary Fund are providing bailout funds while the Greek Parliament is passing brutal austerity measures that cut back on public sector salaries and benefits and selling many state-owned assets.

Greece’s bond rating makes it worth less than the paper it is printed on.

Is this ringing a bell for Harrisburg residents?

It is almost eerie how similar Harrisburg's fiscal situation is to Greece's.

While the IMF pushed for Greece to adopt austerity measures, Pennsylvania lawmakers are pushing for Harrisburg's City Council to adopt the state-sponsored austerity measure known as Act 47.

Politicians in both Harrisburg and Greece used faulty accounting maneuvers that have left them awash in red ink.

Greece used the gimmickry to get into the European Union. Harrisburg used it to renovate its infamous trash incinerator which, let's just say, did not come out quite as cost effective as initially planned.

Rigging the checkbook to trick creditors is easy when it isn’t your money to spend. That is a universal lesson politicians learn all too well.

Keeping an impending fiscal crisis under wraps is relatively easy to do in a booming economy. A continual stream of tax revenue usually provides cover for budgetary shortfalls.

If there is one thing we will learn from the Great Recession, it's that the public sector of state, local and federal governments is no longer sustainable without a robust economy. Harrisburg and Greece are learning this lesson more than others.

The kicking of the fiscal can down the road is slowly coming to an end.

Political leaders in both Harrisburg and Greece are going to face the cold, hard truth: As long as the economy remains in the doldrums, there will be default.  Plain and simple.

Most economists such as Nouriel Roubini, a/k/a Dr. Doom for his prediction of the 2008 crisis, have declared that a default by Greece is inevitable.

With state Sen. Jeff Piccola pushing through a plan for the state to take over running Harrisburg if city officials reject the state's Act 47 plan for fiscal recovery, it is clear many Pennsylvania lawmakers are convinced that Harrisburg is unable to resolve its problems itself.

Many people know the truth, but those in charge continue to deny it.

Head Euro-Zone Finance Minister Jean-Claude Juncker admitted over a month ago that when dire economic situations become serious "you have to lie.'' And indeed that is what is happening.

Like Greece, the prospect of a Harrisburg bankruptcy would be tantamount to Armageddon, or so Mayor Linda Thompson tells us.

To the contrary, declaring bankruptcy is precisely what Harrisburg and Greece need to do.
Bankruptcy would bring short-term pain but would also put both on more solid platforms by renegotiating labor contracts and imposing haircuts on creditors.

Problem is, both Greece and Harrisburg are now prevented from doing so thanks to the IMF and Pennsylvania lawmakers who care more about preserving their own financial interests rather than the public's financial interests.

In Greece's case, the government sees a shirking of bondholders as the number-one priority to avoid. These bondholders include major banks in Germany, France, the United Kingdom and the United States. Instead of
Greece, it is really these banks that are being bailed out to prevent massive losses on their holdings of Greece debt.

When it comes to Harrisburg, the holding out against bankruptcy is not for the citizens, but to try and save Mayor Thompson’s and the state’s reputation. No one wants to preside over the bankruptcy of a capital city, especially a mayor or the senator who represents it.

Unfortunately for both, the world economy is beginning to slow down.

China's inflationary-induced growth is starting rear its ugly head.

The Federal Reserve's QEII policy has just ended. It failed to make a dent in the unemployment rate.

Greece may have been bailed out again, but all it did was put another Band-Aid over the crack of a decaying dam.

Once Greece eventually drops the euro in favor of the drachma and puts the printing press on high, Ireland and Portugal will follow like dominoes.

When, not “if,” Spain needs a bailout, all bets are off.

The economic future right now is bleak.

Yet Mayor Thompson and Senator Piccola have opted for preserving their reputations rather than being adults.

Denying the obvious is the equivalent of peeing in the wind.

It solves nothing.

The sooner Harrisburg deals with the crisis, the sooner we can all stop having visions of the Parthenon on City Island.

James E. Miller, a graduate of Middletown Area High School and Shippensburg University, writes political analysis and commentary on his blog, Miller’s Genuine Draft, at http://millergd.blogspot.com.
I should point out that "peeing in the wind" was originally "pissing in the wind," but I think most people will get it.

There were a few good interviews today, first is Bloomberg with Jim Grant.

Grant is on point like usual.  Yes, we will eventually be returning to a gold standard and yes the U.S. debt ceiling debacle is a sham.  The ceiling will be raised, probably in the next few days, and D.C. will continue gorging itself on buying votes.  All we will be doing is getting a Mastercard to pay for our Visa bill.  That of course would be fraud under most circumstances, but theses are politicians we are talking about.  I really enjoy Grant's comment on the thirty year Treasury rally that seems to be lead by an idiotic belief that the Treasury's have some kind of intrinsic value and that the dollar being the reserve currency of the world is not actually a good thing since it comes with so much responsibility.  And we know how responsible our wonderful leaders in Congress are.

Next up is a great interview of Doug Casey on the Lew Rockwell Show which I unfortunately cannot imbed.  Anything Casey says or writes is worth checking out and this is no exception.  To sum it up, Casey basically warns that U.S. citizens should begin diversifying their financial portfolio internationally.  Casey and Rockwell both predict another Depression coming which will have high bouts of inflation rather than deflation that carried on through the Great Depression.  It will all be followed by another war of course.  Now rather than the federal government swooping in and confiscating gold during the Depression, Casey is worried more about financial controls being implemented that keep capital within the U.S.  Frankly, this type of prediction is not at all farfetched.

Last is John Taylor with Bloomberg who predicts gold will hit $1,900 by October and then plummet, can't imbed this one either.
While Taylor may be right about gold, he is another Keynesian quack if he thinks a weaker Euro will benefit smaller countries in the long run and that the dollar will be fine in the long run.  Taylor, like Casey and Grant, is predicting a severe economic downturn soon (next year for Taylor) which will be worse than what the world saw in 2008.  I love his prediction on QEIII basically financing government "make work" programs but he is overly optimistic if he thinks Bernanke is gonna wait till next year to turn the printing press on again.  He doesn't even acknowledge excess reserves that are starting to enter the system.  Overall, Taylor makes some decent predictions, but his Keynesian leanings and praise for weak currencies leave him ignorant of any stable economic theory.

Charles Hugh Smith of Of Two Minds is out with another handy "how to" guide, this time on how to know when housing has hit its bottom:
Has housing bottomed? Here is the sure-fire way to tell:
Stories titled "Has housing bottomed? Here's how to tell" have vanished for lack of interest.
The absence of stories about the bottom in housing will mark the final nadir, because the real bottom can only be reached when everyone has abandoned housing as a pathway to easy money. Only when the public and investor class alike have completely lost interest in real estate as a "sure-fire" investment can the real trough be reached.
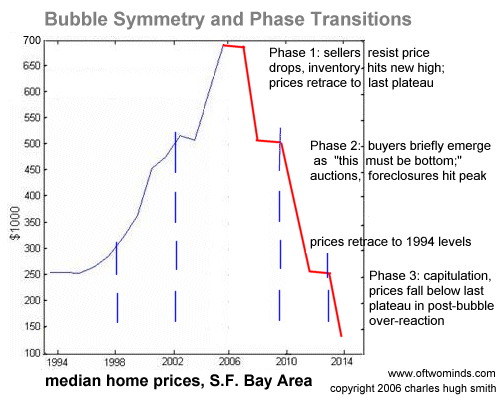
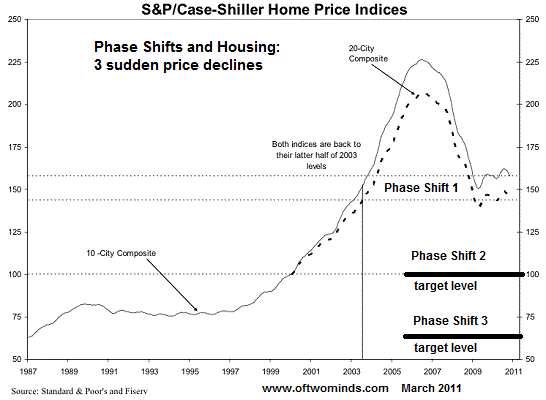
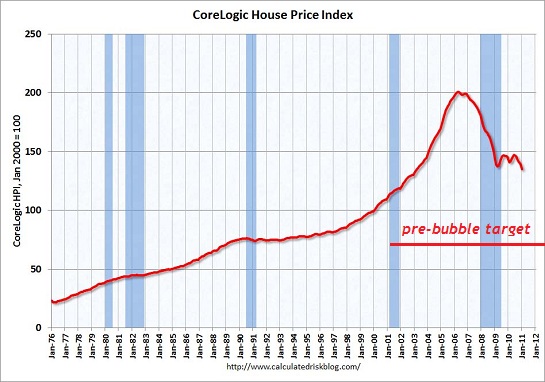
Smith also provides these nice graphs to illustrate where we are in the housing market:
I believe Mish has pointed out the above graph before, but it is still worth mentioning.  Like most financial analysts, Smith is right that housing has yet to hit its market clearing level but we are getting there.

As many readers know, I am a big fan of contrarian economic views and the impeccable Bill Frezza obliges me today with his wonderful Forbes article entitled "Give Greece What It Deserves: Communism"  Here are some excerpts:
Once in a great while an opportunity comes along to deliver justice to a people, giving them what they truly deserve. Greece’s time has come.
It must be dawning on all but the most obtuse member of the banking elite that they can’t possibly steal enough money from German taxpayers to save the Greek government from default. Put it off, maybe, but collapse is inevitable.
Once this happens, what is the purpose of casting Greece into some selective temporary financial purgatory where the irrelevant Greek economy can continue embarrassing anyone foolish enough to lend their dysfunctional government a dime? Why not go all the way and give the country what many of its people have been violently demanding for almost a century?
Let them have Communism.
The land that invented democracy used it to perfect the art of living at the expense of others, an example all Western democracies appear intent on emulating. Being the first to run out of other people’s money makes Greece truly ripe to take the next logical step beyond socialism.
As wrenching as it will be we can take comfort in the fact that Greece doesn’t have much of an economy to disrupt. The only Greek industry that’s worth a damn is tourism, rapidly collapsing as travelers get tired of being stranded by strikes while dodging Molotov cocktails. The rest of us can find plenty of other sources of lamb chops, yogurt, and olive oil. They crushed the concept of private property long ago under the burden of environmental, cultural, and social regulations that govern land use. Wouldn’t it be instructive to let them have a go at building a workers’ paradise to remind us what state enforced equality looks like?
Frezza nails it like always.  The next logical step for Greece really is communism considering the massive and violent protests going on to preserve government transfer payments and rent-seeking.  If they really put their faith in the government, give'em what they deserve!

Update- So you know how Paul Krugman and ilk bitched about the warnings of "death panels" during the debates on Obamacare?  Well this is what we have to look forward to:
‘The NHS was born out of a long-held ideal that good healthcare should be available to all, regardless of wealth. That principle remains at its core. With the exception of charges for some prescriptions and optical and dental services, the NHS remains free at the point of use for anyone who is resident in the UK.’ So says the NHS Choices website itself. But if you smoke or you’re a bit chubby, that statement is no longer true.
n December last year, the Sunday Telegraph reported that NHS bosses in Kent had decided that smokers who required ‘non-urgent’ operations, like hip replacement or cataract removal, would either have to quit before they could join the waiting list or take part in a 12-week smoking cessation course. People with a body mass index (BMI) over 30 – classified as obese – would have to take part in a three-month diet programme in order to get on the waiting list. This week, it seems the idea has spread. According to the doctors’ magazine, Pulse, the NHS in Hertfordshire is planning similar restrictions to the ones proposed in Kent, with smokers and overweight people kept off waiting lists while they mend their wicked ways.
Not exactly "death panels" but its the same concept.

Whenever I argue with others on the HuffingtonPost (I am at 56 fans!) no matter how many times I try to explain that minimum wage laws cause unemployment, they don't seem to get it.  Well here comes William Evan and David Macpherson of Investor's Business Daily to the rescue:
Our new research, recently released by the Employment Policies Institute, suggests that increases in the minimum wage at both the state and federal level since 2007 are partially to blame for the crisis in employment for minority teens.
Most labor economists will tell you that minimum wage increases lead to decreased employment among workers with the least skills. A survey of more than 100 studies on the subject by Drs. David Neumark and William Wascher confirms this fact: A sizable majority, including 85% of the studies the authors identify as providing the best evidence, show disemployment effects following a mandated wage increase.
Our research adds to this literature while uncovering additional information. Using Current Population Survey data from the last two decades, we focused on males between the age of 16 and 24 without a high school degree — a vulnerable group more likely to be displaced as a consequence of rising labor costs.
With a dataset of more than 600,000 observations, we were able to examine in-depth the employment histories of white, black and Hispanic males. We discovered that not every race and ethnicity was affected equally by minimum wage increases at the state and federal level: Each 10% increase in the minimum wage was accompanied by a decrease in employment of 1.2% for Hispanic males, 2.5% for white males and 6.5% for black males.
So last election cycle, Ron Paul received more donations from active duty military personnel than any other Republican candidate.  Most veterans I talk to who aren't incredibly old seem to always agree that our foreign policy is joke.  It looks like the trend is continuing:
Wading through the data in the Federal Election Commission's report for second quarter fundraising this year, activists at the popular Ron Paul website, Liberty Forest, crunched the numbers and reported that their candidate had outraised every single other Republican candidate from sources that list the military as their employer, and had even outraised America's sitting Commander-in-chief, Barack Obama.
Here's the breakdown:
Cain - $6223
Romney - $5000
Bachmann - $2550
Newt - $1025
Pawlenty - $250
Santorum - $250
Johnson - $0
Total GOP (excluding Ron Paul) - $15298.00
Paul - $36739.79
Obama - $28833.99
Update 2- Wow, check out this fascinating Bloomberg profile on Mr. Big Short himself Michael Burry who famously shorted the housing market before it was the hip thing to do and was paid off handsomely.  He was immortalized in Michael Lewis' bestseller "The Big Short."